
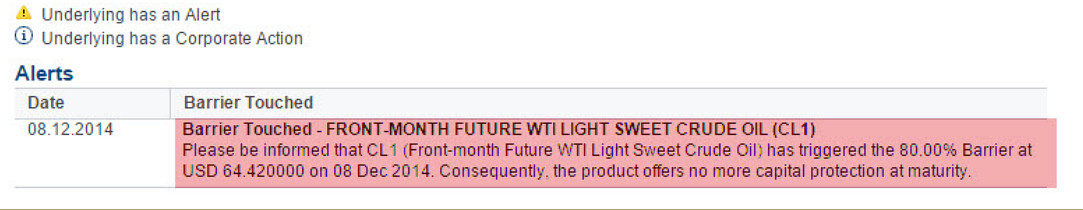
All of these “notes” are simply bundles of risk-free bonds subsidized by written derivative premiums on oil-prices – and sold to greater-fool yield-reaching muppet investors around the world who never saw a short-term trend they did not extrapolate – the question is – who is on the other side of all these notes? Especially now that capital is actually being eroded instead of simply less gains…
h/t Melinda Romanoff, who adds;
The net effect of those Crude Oil Structured Notes is that any of the margin inside those things would wipe out any margin for other trades, a k a stocks, and force a sell off with them. Another side effect of the new Corzine Rule, leave absolutely no excess margin in any account, lest your broker use it for their own trading account.
So every thing goes out with the Structured Note bath water.
I wonder who wanted these things put together to short them……
Related: It’s Not Oil That Is Causing The Slump, It’s The End Of QE
With the oil cartel manipulating oil prices and the currency speculators suspiciously tanking the Ruble at the same time, it’s obvious someone is out to break Putin’s back. Canada can ride out the oil pricing storm but Putin will have some ‘splainin to do to oil sales dependent Russians caught up in an economic tail spin.
With the west virtually bankrupt, NATO in disrepair and the US crippled by weak leadership and socialist klepto economics, let’s just hope Putting doesn’t decide to get the economy going by invading a neighboring satellite (say Estonia or Ukraine) to get the the Ruski economic engines grinding out a healthy war economy again. Cold war II anyone?
motorization?
Surely he means monetization.
Asymmetric bets on “commodity prices [oil] will never go down again.”
–
For many years now Oil Speculators have Shellacked our asses at the gas pumps.
Now they are in trouble because of what they thought were guaranteed oil price increases and loss their gambling gains?
ASK ME IF I GIVE A SHIT?
I have been assured, time and time again, by all manner of anonymous web commenters, that we are running out of oil and the price can only go one way.
Many of these people point to models that prove it, and are also big believers in catastrophic global warming.
Saudi Arabia punishing Russia for their support of Iran? Who knows at this point what’s driving this. The whole world is one giant Rubik’s cube right about now.
The whole world is broke so why Putin should be more at risk is questionable. In fact his popularity has been enhanced not destroyed. Stratfor commented that Russians have a far greater ability to handle ‘tough’ times than the west appreciates. Putin could easily seize foreign investments in retaliation. I highly doubt he does more than encourage dissent within the neighbourhood than actually use force. He has been signing deals that do not use the $US. How much does Russia import in $US is the big question and how easily can it be replaced.
Mauldin recently stated that Texas created 40% of US job growth. A huge majority of that was oil related growth. Spin a 3:1 indirect job creation and he questions how strong the USA recovery actually is. Combine that with the value of the jobs created in that oil jobs are usually high paying vs a MacJob in Cali or NYC. The importance of all this is a vein of thought that the USA can drag the world towards recovery which has driven markets upwards. The thoughts above suggest otherwise.
Governments around the world continue to add debt at unprecedented rates no matter if communist, Islamist, dictatorship and democratic. Deflation is the elephant in the closet and medicine to cure it is not embraced by anyone.
Google ‘news for deflation’. Twelve months ago there was nary an article on deflation – this morning almost 9 million of them.
Seems that political leaders and central bankers around the world are in a panic – worried that their money printing ways have not created enough inflation lately (aka currency debasement at the expense of cash holders) They are freaking out that, horrors of horrors, consumers will not be stampeded into spend spend spend if the mindset of things always being more expensive down the road becomes passe’.
Oh, and by the way, inflation by way of inducement through ‘money printing’ is a handy way of reducing effective gov’t debt.
But now so many “economists” (read ‘the Paul Krugman types’) are beside themselves with worry that governments are so indebted because of their money printing ways they may have to, horrors of horrors, ease up on … yes, ‘quantitative easing’. If QE is reduced they all worry that deflation may very well set in. If consumers, that engine of “growth”, ever catch on that deflation means lower prices down the road, then they will simply delay spending. The central bankers seem worried that consumers will never spend again in a deflationary scenario. mmmm because we all know that consumers do not spend because they actually might need something but because it will cost more tomorrow – witness the Black Friday* panic phenomena.
Now throw on top of all their worry the collapsing price of oil (glut?? hello Peak oil ??) and the threat that it could really force a downward deflationary spiral. This just cannot be good because we all know low energy prices are not good for consumers or something. But will cheaper oil not free up money that could just be spent on other goods? Yes but the inflation stokers worry, while it may be a wash, they do not want a wash – they want inflation rates of at least 2% and will print money to achieve it.
But Japan has been trying to reflate by way of QE for some twenty plus years now. But all they have achieved is to have the highest debt to GDP ratio of any major economy. Why, you say? Because of demographics. Japan also happens to have the fastest population decline of any of the major economies. aka if there are not enough young people coming along to buy the old people’s stuff why build new things? Maybe economies can grow without population growth but I don’t know how.
Do I have all this right?
Ron said: “Maybe economies can grow without population growth but I don’t know how.”
Two words Ron. TAX. CUTS. With tax cuts all the perverse backwards incentivization stops, and people are free to invest their money in their own ventures again.
I don’t know if Japan can be used for a model of anything though. Japan these days seems ever more f-ed up than the day before. I get the impression they still haven’t recovered as a culture from the nuclear @ss kicking of WWII, which they know to be a well deserved @ss kicking due to their own egregious behavior. An entire people don’t get over something like that so easily.
Their popular music is Korean and American, their youth culture is some kind of unholy combination of Hello Kitty and upskirt porn with Geisha thrown in. Some of the “services” available in tea houses and other such places are so sad, like Maid clubs where chumps pay girls in cutesie maid outfits to -talk- to them. No lap dances, just getting paid attention to. Other bars cater to women, same idea. This is not some fringe nut thing, or even the leagal-but-skeevy status of strip clubs in North America. This is mainstream stuff in Japanese cities. Like McDonalds.
Japan also is heavy with suicide, people capping themselves in all sorts of inventive ways. Japanese suicide rate is about 21/100,000, by contrast Canada’s is about 11/100,000.
Symptomatic of a widespread cultural malaise, IMHO. Millions of people too emotionally fragged to give a sh1t. Not someplace to look for major growth.
Here’s one opinion.
The Fed is not monetizing the debt.
http://pragcap.com/pomo-flip-matter
“If consumers, that engine of “growth”, ever catch on that deflation means lower prices down the road, then they will simply delay spending.”
Incorrect. The Marshmallow Experiment alone proves that upwards of 65% of the population has zero ability to delay gratification. Even if they know that delayed gratification will absolutely bring them big dividends down the road they simply cannot wait.
Who buys them? Same kind of chump who buys EQ strutured notes from a Canadian retail bank….
Typically, there’s no margin required, no? You pay principal up front, and the note pays you out at settlement an amount equal to the given payoff scheme – principal plus return (positive or negative). For the sell-side, it’s a nice barrier option, with far more limited downside. The buy side guy doesn’t post margin, since he’s already paid it at origination. The sell-side guy is in the money, and has already rehypothecated, so what’s the rag?
“I’ll tell you who loses – the client” … senior prop-trading manager at a major FI, in a meeting with me last year.
Now the client has to recalibrate his present value, and if he’s a big player, his CET1 ratio, to keep the badboy regulators happy. That’s gonna cause a squeeze on capital. As well, the ALM crew will suddenly be looking at recalibrating the swap curve, based on a capital squeeze scenario. Hence spreads get bumped, but nobody’s reg or economic cap model can quite catch that effect on a forecast basis (except for the CVA and FVA desks – they are good at that crap for the OTC stuff).
What you need to be watching for is not the exotic, barrier, WO/BO KO/KI stuff, but the vanilla payer-receiver CO swaps, and any (and I mean ANY) NG or oil basis trades. Those are blown apart so far in/out of the money, that your small-time cpty is likely gonna tell you to get stuffed, and bail on you. Or find a clever way to stiff you at ISDA, since your intern didn’t quite book the trade right.
Structs like these are not that high-leverage, since the writer already has the jackpot in possession (modulo no accident in the repo market), and has thoroughly hedged out $120 Oil in the basis swaps and futures market.
I am far more interested in what this sort of cap squeeze does to the OIS rate, as the best snapshot we have for the time-value of money.
By the way, you can synthesise a lot of these structs easily using a HY bond on an oil exploration team – upside limited to YTM, downside could the whole thing. So no big surprises there, I’m afraid.